Abstract
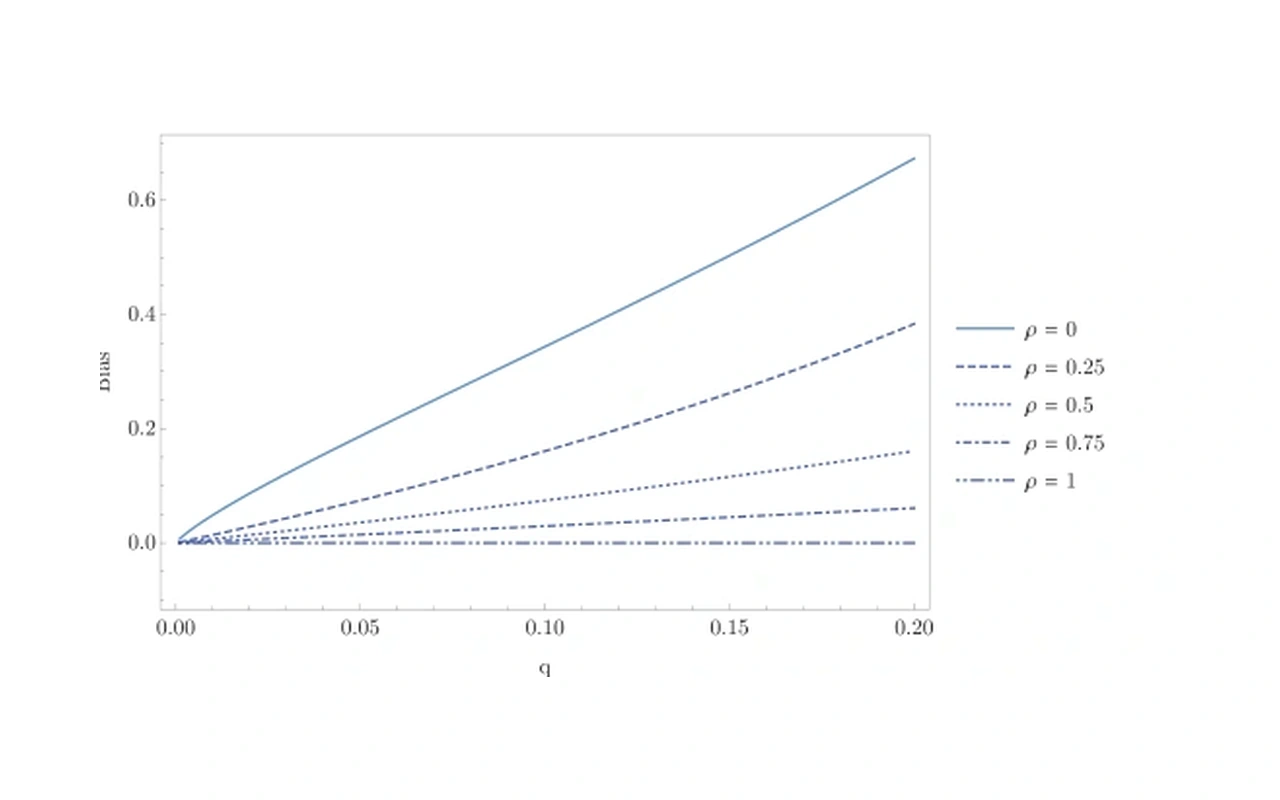
Underreporting and undersampling biases in top-tail wealth, although widely acknowledged, have not been statistically quantified because they are not readily observable. We exploit the functional form of power-law-like regimes in top-tail wealth to derive analytical expressions for these biases. Using German survey microdata and a rich list, we show that tiny differences in non-response rates can produce tail-wealth estimates that differ by an order of magnitude. Underreporting compounds the problem, and estimates of totals in scale-free systems can become spurious. The results also question whether available data can reliably distinguish scale- or type-dependence in returns to wealth from statistical bias.
Citation
Jan Schulz & Mishael Milaković (2023): How Wealthy Are the Rich?. Review of Income and Wealth 69(1): 100–123.